
Organising a Land Valuation for Probate and Estate Planning
Introduction
When someone dies and their estate includes land — a vacant block, a rural holding, a share in a farm, or simply the land under a house — one of the first practical questions an executor faces is: what’s it actually worth? Unlike shares or bank accounts, land rarely comes with a tidy statement showing its value on a given date. If there’s no recent sale or contract to point to, that number has to come from somewhere, and a rough guess isn’t going to satisfy the Australian Taxation Office, a probate registry, or beneficiaries who don’t entirely trust each other’s estimate.
This matters more than most executors expect. The value placed on land affects capital gains tax down the track, the fees paid to apply for probate in some states, and how fairly an estate is divided when land is one of several assets being split between beneficiaries, making a professional valuation of land assets an important step for many estates. It also matters well before anyone dies — families increasingly get land valued as part of planning a will, especially when one person is set to inherit a farm or investment block and others are getting cash or shares instead.
This guide covers when a formal land valuation is actually needed for probate, how it interacts with capital gains tax, what makes land trickier to value than a standard house, and how the same process supports proactive estate planning.
Summary
Land valuations come up in estate matters for a few distinct reasons, and it helps to keep them separate. For capital gains tax, land acquired by the deceased before 20 September 1985 needs a date-of-death valuation because the cost base rules can change under ATO guidance on inherited property and capital gains tax. — without it, there’s no defensible number for a beneficiary to use when the land is eventually sold. For land acquired after that date, the beneficiary generally inherits the deceased’s original cost base instead, so a fresh valuation isn’t always compulsory, though it’s still useful if that historical cost information has been lost. For probate itself, courts generally want an estimate of the property’s value at the date of death to include in the inventory of assets, and in several states the court filing fee is scaled to the gross value of the estate — so an unsupported number can cause problems either way, too low and it may be challenged, too high and the executor pays more than necessary.
Vacant, rural and semi-rural land is often the hardest to pin down, because it may lack a recent sale nearby to compare it to. Executors also carry a duty to treat beneficiaries evenly, which matters most when land is being divided or one beneficiary wants to buy out the others’ share. On the planning side, getting land valued while the owner is still alive can inform how a will is structured, particularly where a farm or block is going to one child and other assets to siblings. In all of these situations, an independent, qualified valuation carries more weight than an agent’s appraisal or an online estimate, because it’s prepared to a standard that will hold up to scrutiny from the ATO, a court, or a family member questioning the figure.
When Does an Estate Need a Land Valuation?
Not every asset in a deceased estate needs a formal valuation, but land is one of the assets most likely to require one, for a few practical reasons.
- There’s often no recent transaction to anchor a value. A share portfolio has a daily market price; land might not have changed hands in decades.
- Multiple parties rely on the figure. The ATO uses it for capital gains tax, the probate registry may use it for the estate inventory, and beneficiaries use it to understand what they’re actually receiving.
- Land held with others complicates things. If the deceased owned land as tenants in common (as opposed to joint tenants, where the surviving owner automatically takes the whole interest), only their share forms part of the estate, and that share still needs its own value.
The exact requirements for probate applications vary between Australian states and territories — the Supreme Court of each state runs its own probate registry with its own forms and process — so it’s worth confirming the specific requirement with the executor’s solicitor. Understanding the difference between council valuations and actual market conditions can also help executors avoid relying on figures that may not reflect the property’s true value. As a general pattern, though, probate applications ask for an inventory of the estate’s assets, including real estate, with an estimate of value at the date of death, and in states like NSW the court filing fee itself increases in bands as the gross estate value rises, which is one more reason the figure needs to be reasonably accurate rather than a rounded guess.
Land Valuation and Capital Gains Tax on Deceased Estates
This is where most of the real financial stakes sit, and it’s also where a lot of confusion creeps in.
Land acquired before 20 September 1985 (pre-CGT)
When someone dies, any land they bought before CGT was introduced gets a mandatory reset: the beneficiary’s cost base becomes the market value of the land on the date the person died. Without a formal valuation from around that date, the beneficiary has no defensible starting point when the land is eventually sold and CGT becomes payable on the gain. This is the clearest case where a date-of-death valuation isn’t optional in any practical sense — it’s the only way to establish a cost base at all.
Land acquired on or after 20 September 1985 (post-CGT)
Here, the beneficiary generally inherits the deceased’s original cost base — what they paid, plus eligible costs — rather than a fresh market value at death. A valuation isn’t always strictly required in this scenario, provided the original purchase records still exist. In practice, though, those records are often missing decades later, which is when a retrospective valuation becomes the only way to reconstruct a workable figure.
A common misconception worth correcting
Many people assume inherited property automatically gets the same CGT treatment as a family home. The two-year main residence exemption that can apply to an inherited dwelling only applies to a dwelling — a house someone actually lived in as their main residence. Vacant land, a rural block with no residence, or land held purely as an investment doesn’t qualify for that exemption, regardless of how it’s eventually used. If that kind of land is sold by the estate or a beneficiary, CGT applies on the ordinary cost-base rules above, which makes getting the valuation right at the outset more significant, not less.
The Probate Process and Valuing Land Assets
Alongside the tax question, there’s a separate, more immediate one: what does the executor need for the court?
Most probate applications require the executor to prepare an inventory of the deceased’s assets, with real estate identified by its title details and an estimated value at the date of death. This is generally an estimate for the purpose of the application rather than a full valuation report — but “estimate” still needs to be reasonably supportable, because it’s a sworn or affirmed statement to a court. Where the land’s value is uncertain, contested by beneficiaries, or significant enough that getting it wrong has real consequences, executors commonly commission an independent valuation rather than relying on a council rates notice or an agent’s off-the-cuff figure.
There’s also a fairness dimension that sits outside the court process entirely. An executor owes a duty to act even-handedly between beneficiaries. If a farm, a rural block or a set of vacant lots is being divided — or if one beneficiary wants to keep the land and buy out their siblings’ interest — an independently assessed value protects the executor from claims of favouritism and gives everyone a figure they can actually rely on, rather than one party’s opinion of what it’s worth.
Why Rural, Vacant and Semi-Rural Land Can Be Harder to Value
Valuing a suburban house is relatively straightforward: there are usually comparable sales down the street. Land is often a different exercise.
- Limited direct comparables, particularly for larger rural holdings, irregular parcels, or land in areas with low sales turnover.
- Zoning and planning overlays that affect what the land can be used for, including environmental, bushfire or flood overlays that a general estimate is unlikely to account for.
- Highest-and-best-use questions, such as whether a block’s value lies in its current agricultural use or in its potential for future subdivision or rezoning.
- Access, easements and encumbrances, including shared driveways, powerline easements or native vegetation restrictions that can meaningfully affect value but aren’t visible from the street or a rates notice.
These are exactly the kind of factors a qualified valuer is trained to identify and account for in a formal report, and exactly what tends to get missed in a quick online estimate or a verbal opinion from an agent.
Land Valuations as Part of Estate Planning
Valuations aren’t only relevant after someone has died. Increasingly, families use a formal land valuation while the owner is still alive, as part of putting together or updating a will.
This comes up most often when land isn’t easily divisible — a farm, a rural block, or a single investment parcel that’s going to one child while others receive different assets. Without a current, independent value, it’s hard for a will-maker to judge whether the overall distribution between beneficiaries is actually balanced the way they intend. A documented valuation, obtained at the time the will is prepared, gives the family a defensible reference point and can reduce the likelihood of a family provision claim later, where a beneficiary argues the will didn’t adequately provide for them.
The same applies where land is being transferred into a trust, gifted to a family member below market value, or moved as part of restructuring how a family holds its property — all of these can trigger capital gains tax or stamp duty based on market value, so getting an independent figure at the time of the transfer matters just as much as it does after a death.
How a Professional Land Valuation Differs from an Agent’s Appraisal
It’s worth being clear about this distinction, because the two are often confused. A real estate agent’s appraisal is generally a free, informal estimate designed to help price a property for sale — useful for that purpose, but not independent, not prepared to a recognised valuation standard, and often pitched toward the higher end to win the listing. It’s not something the ATO, a court, or a sceptical beneficiary is likely to accept as evidence of value.
A formal land valuation, by contrast, is prepared by a qualified, independent valuer, sets out the methodology and evidence used to reach the figure, and is intended to withstand scrutiny — whether that’s from the Tax Office checking a cost base, a court considering a probate application, or one beneficiary questioning whether another is getting a fair deal.
What to Provide Your Valuer
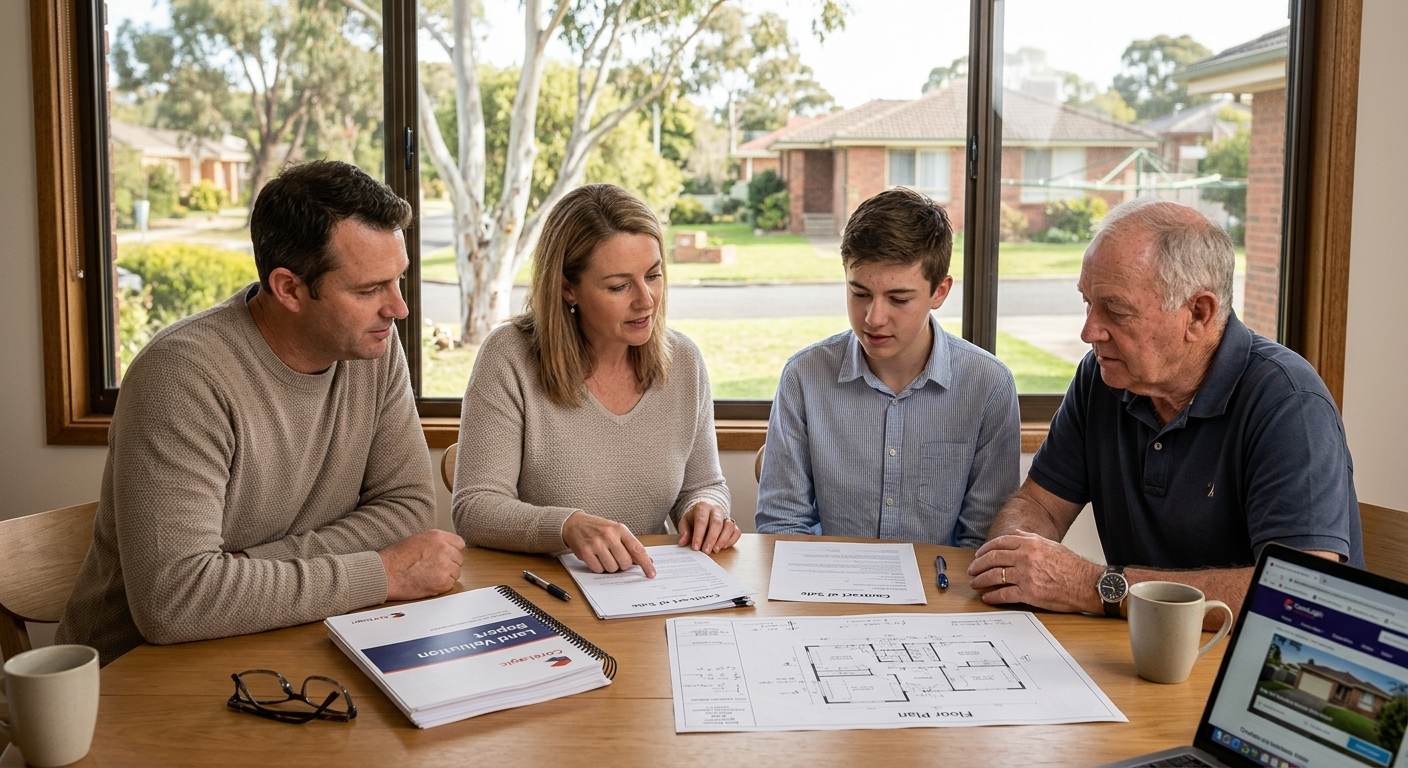
Getting a land valuation done efficiently usually comes down to having the right documents on hand:
- Certificate of Title (or details to help the valuer obtain it)
- Death certificate and grant of probate, if already issued
- Any survey plan or recent zoning certificate
- Council rates notice
- Details of any lease, occupancy or agricultural use of the land
- Any earlier valuation or contract of sale, even an old one
- Reasonable access to inspect the land
FAQs
Do I need a formal valuation for probate, or can I just use the council rates notice?
A rates notice reflects a council’s valuation for rating purposes, not market value, and the two can differ significantly. It may be enough for a very low-value or uncontested estate, but for anything of real value, or where the figure will later be used for CGT, an independent valuation is the safer basis.
What date should the land valuation be based on?
For CGT and probate purposes, the relevant date is the date the person died, not the date the valuer inspects the property or writes the report. A valuer can prepare a retrospective valuation assessing what the land was likely worth on that earlier date.
Who pays for a land valuation during probate?
It’s typically paid from the estate as an administration expense, the same as other costs of managing the estate, though this can vary depending on the will and the executor’s arrangements.
Can beneficiaries dispute a land valuation?
Yes. This is one of the main reasons executors commission an independent valuation in the first place — a report from a qualified, unrelated valuer is harder to challenge than a figure the executor or one beneficiary proposed themselves.
Does vacant or rural land get any CGT exemption like a family home does?
No. The main residence exemption applies only to a dwelling that was actually lived in. Vacant blocks, farmland without a residence, and investment land don’t qualify, so CGT will generally apply on any gain when the land is eventually sold.
Can I get a valuation now for a death that happened years ago?
Yes, this is a retrospective valuation, and it’s common where an executor or beneficiary didn’t organise a valuation at the time and now needs one to complete a tax return or resolve a dispute.
Conclusion
Land rarely values itself the way a bank balance does, which is exactly why probate and estate planning so often turn on getting a proper valuation. Whether it’s a pre-CGT block needing a date-of-death figure, a rural holding being divided between beneficiaries, or a parcel being valued ahead of a will, an independent, defensible valuation protects everyone involved and avoids disputes that a rough estimate can’t withstand.
Need a Land Valuation for Probate or Estate Planning?
If you’re an executor, beneficiary, or planning your own estate and need an independent, defensible valuation of land assets, Valuation HQ can prepare a report suited to probate, CGT or family planning purposes. Call Valuation HQ on +61 438 080 786 to discuss what’s involved for your situation.